Use one page for the month map, the working plan, and the next three decisions—then update it in a short weekly routine.
A monthly financial planner should not make you hunt through five pages before you can answer one simple question: what does this month need from me?
The most useful setup is often one working page. It brings together the money arriving, the commitments already spoken for, the flexible spending you can still influence, and the next decisions that keep the month moving.
This guide shows how to build that page around three blocks: the month map, the working plan, and the decision queue. It is not a replacement for your bank records, bills, or detailed transaction history. It is the small control surface you return to throughout the month.
Why one monthly money page works
A budget can be accurate and still be hard to use. The problem is often fragmentation: income lives in one table, bills in a calendar, savings goals somewhere else, and spending totals in an app you rarely open.
Consumer.gov describes a budget as a monthly plan that compares income with bills and other expenses, then uses what happened this month to plan the next one. The Consumer Financial Protection Bureau separately offers an income tracker, spending tracker, bill calendar, and cash-flow budget. Those are useful records. Your one-page planner does a different job: it summarizes the few figures and dates you need for the next decision.
Your bank and statements hold the complete record. The monthly page shows the current plan, the latest trustworthy totals, and what you need to do next.
The three-block monthly planner layout
| Block | Question it answers | What belongs there |
|---|---|---|
| 1. Month map | What money and commitments define this month? | Expected income, fixed bills, due dates, nonmonthly set-asides |
| 2. Working plan | What can I still spend, save, or redirect? | Flexible caps, current actuals, savings or debt target, buffer |
| 3. Decision queue | What are the next three useful actions? | Decision, owner, deadline, status, next review date |
Keep detailed transactions, receipt images, and long notes outside this page. Link to them if needed. The overview stays useful because it remains small enough to scan in under a minute.
Block 1: Build the month map
Start with the facts that shape the month before discretionary spending begins.
- Expected net income: include paychecks and other income you reasonably expect to receive this month.
- Fixed and known bills: rent or mortgage, utilities, insurance, minimum debt payments, subscriptions, and other commitments.
- Due dates: show the date beside every bill instead of storing it in a separate hidden view.
- Nonmonthly set-asides: add the amount reserved this month for annual premiums, maintenance, holidays, school costs, or other irregular expenses.
- Starting buffer: record only the amount intentionally available for this month's plan, not every dollar across every account.
The CFPB's bill-calendar guidance recommends listing what each bill is for, the amount owed, and the due date, then checking the calendar weekly. Bringing those three fields into the month map helps you see not only how much is committed, but when pressure points arrive.
If your income varies, do not force a best-case estimate into the page. Use a conservative income floor for the base plan and keep less-certain income in a separate “not assigned yet” line until it arrives.
Block 2: Create the working plan
The second block is where the month stays alive. It should compare a few planned limits with current actuals without becoming a full transaction register.
Choose three to six flexible categories that genuinely change your decisions. For many households, that might be groceries, dining out, transportation, household purchases, personal spending, and entertainment. Show four fields for each:
- planned amount;
- spent so far;
- remaining amount;
- one short note only when an adjustment is needed.
Add one priority target below the categories. It might be a savings contribution, extra debt payment, sinking-fund deposit, or buffer goal. Do not display every long-term goal at equal weight. The purpose is to make this month's priority visible.
Consumer.gov's budget worksheet separates monthly income from housing, food, transportation, and other expenses, and it explicitly includes savings in the plan. That supports a simple rule for this block: give saving a planned line rather than waiting to see what happens to remain.
Add a “last updated” date. If the actuals are a week old, the page should admit it. A beautiful dashboard with stale totals is less useful than a plain page with honest data.
Block 3: End with a decision queue
A dashboard becomes useful when it leads to action. Reserve the final block for no more than three open money decisions.
| Decision | Deadline | Next action |
|---|---|---|
| Grocery spending is running ahead | Before Friday's shop | Plan four dinners from food already at home |
| Annual insurance payment is due next month | October 20 | Move the final set-aside to the bills account |
| Streaming service renews soon | October 24 | Review use and cancel or keep |
Write actions that can be completed, not vague intentions such as “spend less.” When an action is done, archive it and pull in the next decision. If the queue repeatedly grows past three items, your page is becoming a task manager rather than a financial overview.
Calculate one monthly planning number
Once the first two blocks are filled, calculate the amount still unassigned:
Expected income + starting buffer − fixed bills − nonmonthly set-asides − flexible spending plan − priority target = unassigned amount
A positive number is not automatically free spending. Decide whether it belongs in the buffer, another savings goal, debt, or a known upcoming cost. A negative number signals that the current plan asks more of the month than the expected income and buffer can support.
Consumer.gov recommends subtracting bills and expenses from monthly income and changing the plan when the result is below zero. Treat that result as a planning signal, not a moral score. Adjust the timing, target, or category caps before the month makes the decision for you.
Use the page in a 10-minute weekly routine
- Confirm the income received since the last check-in.
- Mark paid bills and verify the next due dates.
- Update only the flexible-category totals shown on the page.
- Check whether the priority target is still realistic.
- Recalculate the unassigned amount.
- Choose or update the three decisions in the queue.
- Set the next review date.
The CFPB suggests keeping a bill calendar somewhere you can check weekly. That cadence is enough for many monthly planners: the page stays current without inviting daily budget anxiety.
How to build the page in Notion
Create one page named for the month, then add three simple sections.
- Month map: a compact table with item, amount, due date, status, and type.
- Working plan: a second table for flexible categories plus one callout for the priority target and unassigned amount.
- Decision queue: three cards or rows with the decision, deadline, next action, and status.
If you already maintain separate databases for transactions, bills, subscriptions, or goals, use linked filtered views rather than copying every record. Filter to the current month and show only the properties required for the three blocks.
Use formulas only when they remove a repeated calculation you understand. A remaining amount formula can be helpful. A dense web of rollups is not useful if you stop trusting or updating it.
A broader Notion Life OS example
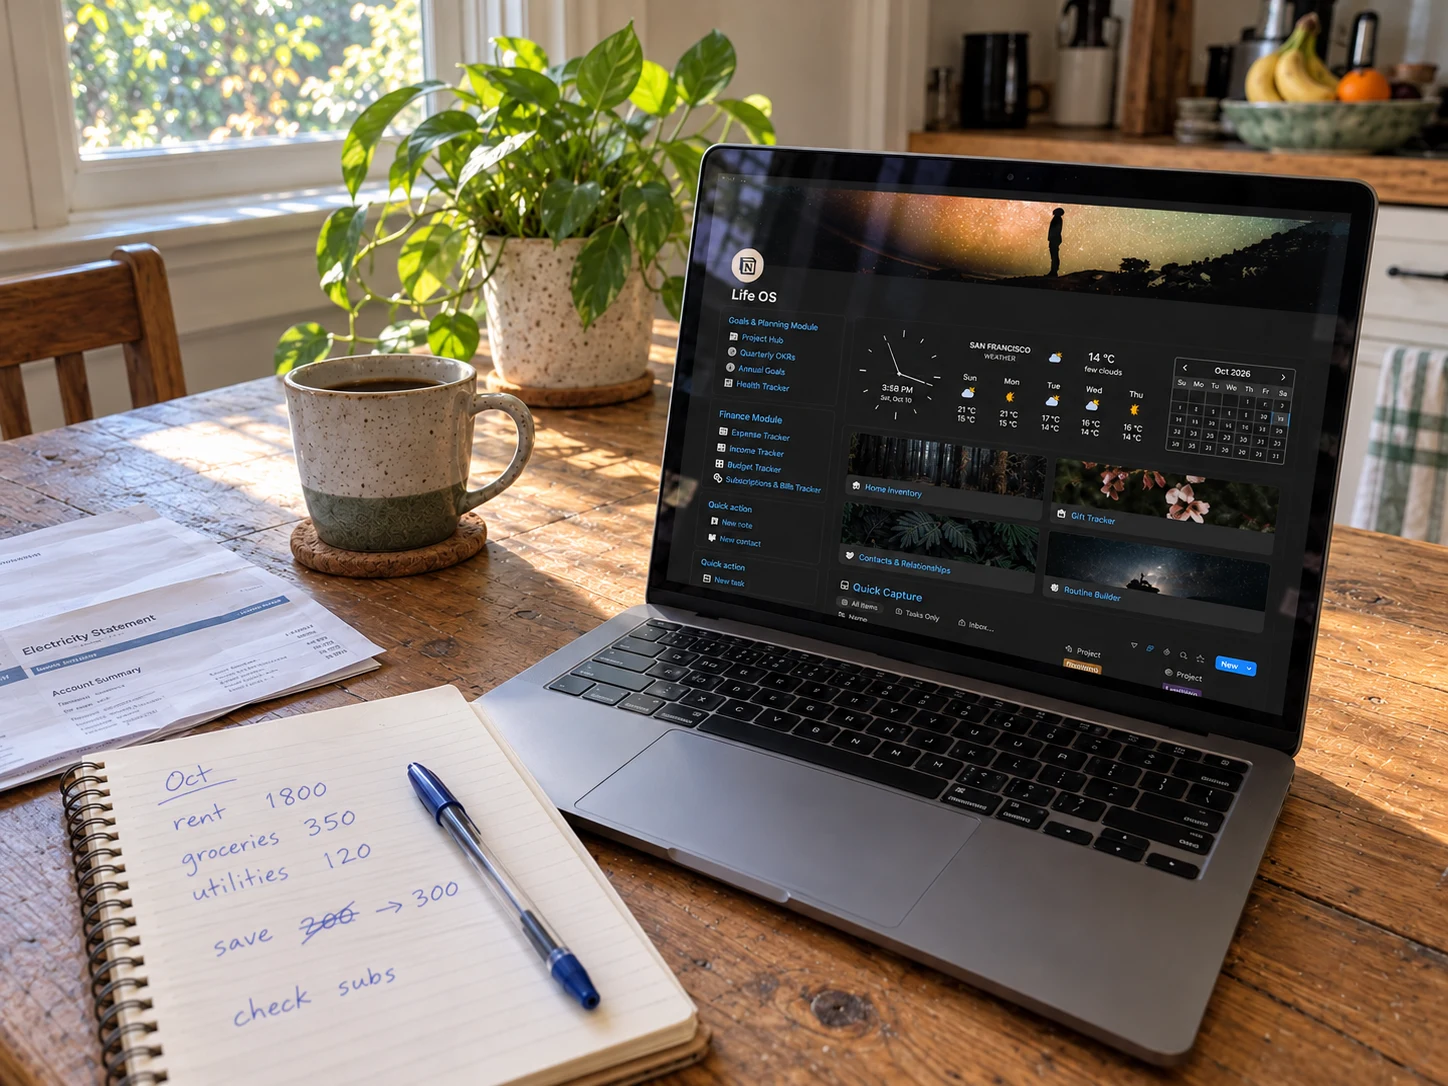
The approved Life OS Notion Template by Dohaforkdp is a broader all-in-one Notion workspace. Its public listing describes a Finance Module for tracking income and expenses, monitoring a monthly budget, and watching subscriptions and bills. The same system also includes dashboard, goals, planning, wellness, learning, and home sections.
That makes it relevant if you want your monthly money overview inside a wider personal dashboard. The public listing does not show a dedicated three-block monthly command page or explain its formulas. The layout in this article is an editorial setup you can build or adapt; it is not a claim about the product's exact internal structure.
The product was not purchased, duplicated, or tested for this article. This description is based on the current public Creative Fabrica card and four visible previews. At the time checked, the card showed 21 additions to favorites and no reviews; those signals can change.
 All-in-one Notion workspace
Life OS Notion Template
A dark Notion workspace whose public listing includes income and expense tracking, a monthly budget, subscriptions, bills, goals, tasks, and other life areas.
See the current template details →Five mistakes that make the page harder to use
- Showing every transaction. Keep the overview summarized and link to the ledger.
- Hiding due dates. Amounts alone do not reveal cash-flow pressure.
- Tracking too many categories. Display the categories that change decisions this month.
- Leaving numbers undated. Add a visible last-updated date.
- Ending without an action. Keep the next three decisions on the same page.
Frequently asked questions
Is a monthly financial planner the same as a transaction tracker?
No. A transaction tracker stores detailed spending records. The monthly page summarizes the plan, current category totals, commitments, and next decisions. You can link the two without displaying every transaction.
How often should I update the page?
A short weekly update works for many people. Update it sooner when income changes, a major bill changes, or you make a decision that alters the plan.
What if I am paid biweekly?
Keep the monthly overview, but show each expected paycheck separately in the month map. If timing is the main problem, use a biweekly budget beside the monthly page.
Should savings appear as an expense?
It can be useful to give savings a planned line so it is part of the month rather than an afterthought. Choose a target that still leaves essential bills and realistic living costs covered.
Do I need a new Notion page every month?
Not necessarily. You can duplicate a clean monthly page, or use linked databases filtered to the current month. Choose the version you will actually review and maintain.
Run the month from one useful page
Your monthly financial planner does not need to contain everything. It needs to show what defines this month, what can still change, and what you will do next.
Build the month map, keep the working plan honest, and limit the decision queue to three actions. Then return once a week. One clear page that stays current is more useful than a perfect system you avoid opening.
Sources
- Consumer.gov: Making a Budget
- Consumer.gov: Make a Budget Worksheet
- Consumer Financial Protection Bureau: Your Money, Your Goals toolkit
- Consumer Financial Protection Bureau: Bill Calendar
- FDIC: Money Smart financial education program
- Creative Fabrica: Life OS Notion Template
This article is educational and does not provide individualized financial advice.
Written by Calm Budgets