The goal is not predicting every month perfectly. It is a system flexible enough to handle a light month and a heavy one.
A college budget usually collapses for a boring reason: income and expenses both change every month, and a budget built for one "typical" month cannot survive a semester that never repeats itself the same way twice.
This guide treats that variability as the actual problem to solve, rather than something to plan around with a single fixed number.
Why a college budget is not just a smaller version of a regular one
Income might be a part-time job, financial aid disbursed twice a semester, occasional help from family, or all three at different times. Expenses swing just as much — a light month, then a textbook-and-supplies month, then a month with a trip home.
A fixed monthly budget assumes both sides stay roughly the same. For most students, neither does, which is why a budget copied from a general template usually stops matching reality within a few weeks.
The goal is not predicting every month perfectly. It is having a system flexible enough to handle a light month and a heavy one without starting over each time.
Plan by semester, check in monthly
Start with the semester total: financial aid disbursements, expected income, and known large costs like tuition, books, and housing. That bigger picture shows whether the semester works before getting into weekly detail.
Within that, check in monthly rather than trying to hold the whole semester's detail in your head at once. A monthly check catches problems while there is still time to adjust.
Handling aid disbursements and irregular income
When a large amount arrives twice a semester instead of monthly, divide it by the number of weeks it needs to cover before spending any of it. Treating a lump sum as "available now" is the most common way a semester's aid runs out before the semester does.
Part-time job income that varies week to week works better averaged over the last month than estimated from a single good or bad week.
A simple monthly check-in
- Confirm what actually came in. Job income, aid, family support — the real total, not the expected one.
- Check against known upcoming costs. Books, fees, a trip home — anything predictable for the coming weeks.
- Adjust the following month's spending plan. A lighter month can absorb more; a heavier one needs more caution.
A realistic example
Imagine a semester that starts with a financial aid disbursement meant to last four months. Divided by week from the start, it becomes a manageable weekly amount instead of a balance that feels available to spend freely in week one. By November, the same method shows enough left to cover December's exam-week expenses without a scramble. This is an illustrative example, not a reported personal result.
What usually breaks a college budget
- Spending a disbursement like it is one month's money. It is usually meant to stretch much further than that.
- Copying a general budget template. Categories built for a stable monthly salary do not fit irregular student income.
- Ignoring small recurring costs. Subscriptions and small daily purchases add up the same way they do for anyone else.
- Checking in only when money runs out. By then, the adjustment is forced rather than planned.
A ready-made starting point
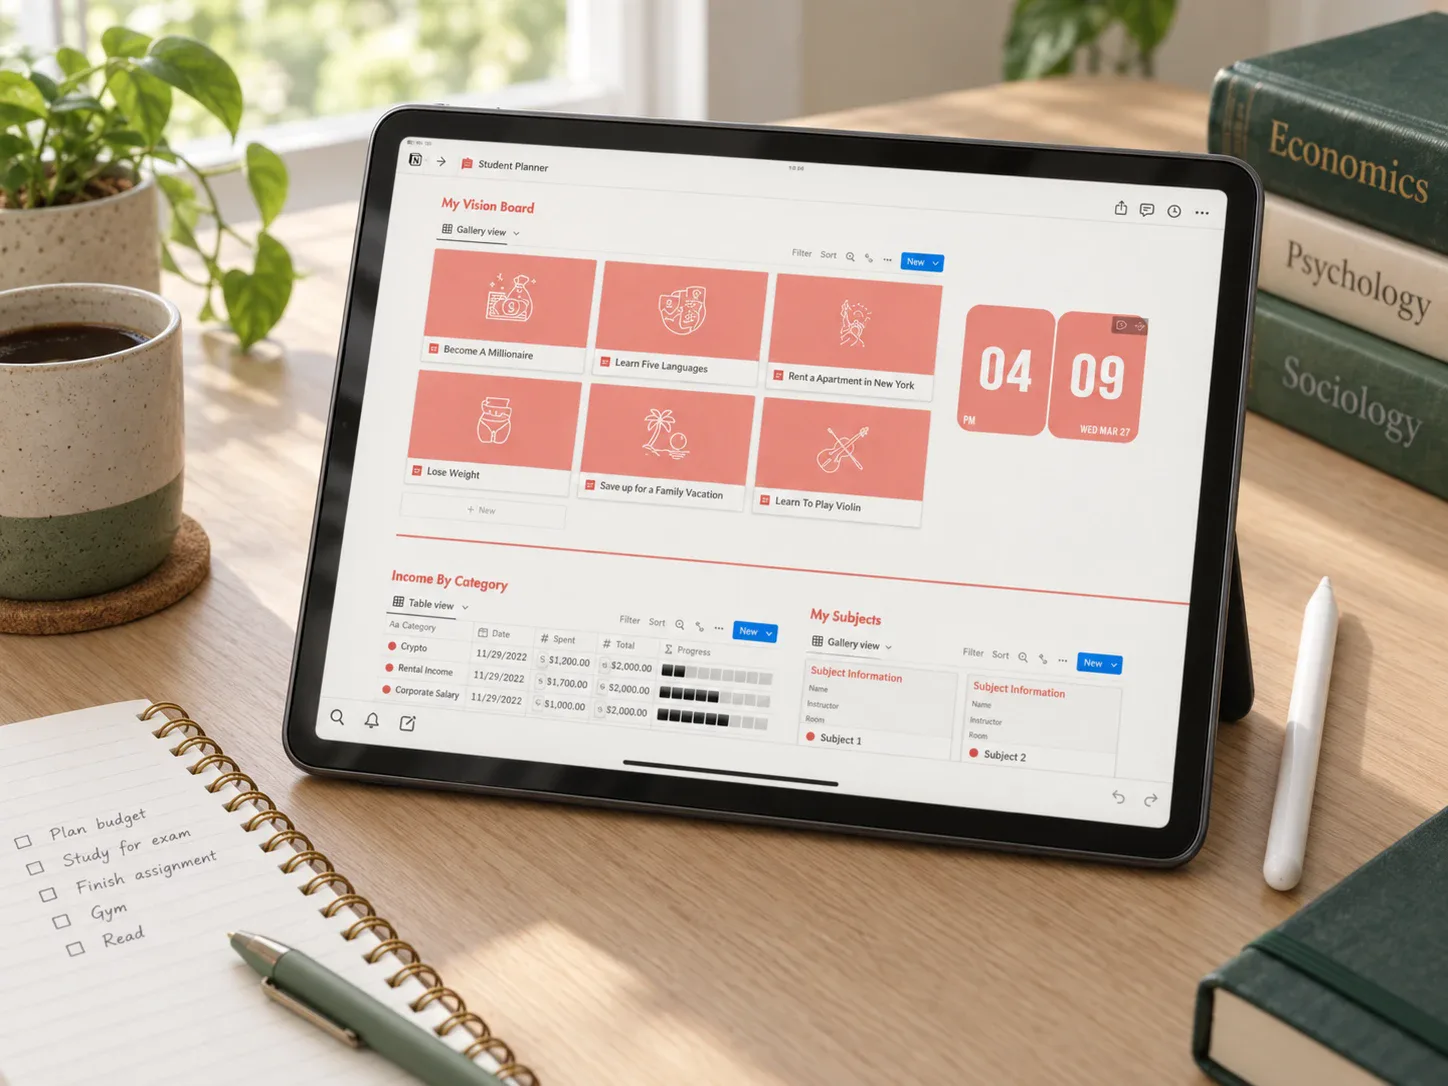 Student budget
Notion Student Planner
Pairs a budget planner with the rest of student life — classes, tasks, and a vision board — so money tracking lives next to the same schedule it needs to work around.
Read the planner guide →Questions people ask before starting
What if my income changes every single week?
Use a rolling average of the last three or four weeks instead of any single week as your planning number.
Should parents or family contributions be tracked the same way?
Yes. Any money you are responsible for stretching across the semester belongs in the same system, regardless of where it came from.
How do I handle a semester that starts mid-month?
Prorate the first partial month rather than forcing it into a full-month box — a partial period is normal for a first semester.
Start with this semester's total
Add up everything you expect to receive this semester and everything you know you owe. That single comparison tells you whether the semester works before you plan a single week of it.
Written by Calm Budgets